Vektorium Master Fund Commentary · September 2026
We estimate for September 2026, the Vektorium Fund Class A was down -1.6% in USD and is up +2.76% for the year. A frustrating month as both our investments in the 30-year US inflation-linked bonds and our globally diversified equity portfolio worked against us. All this, in the backdrop of a very concentrated U.S. large cap equity market, rally particularly in the semiconductor shares.
When we look back at Q3, we see an overwhelming narrowness in equity market performance with non-US equities (MSCI EAFA) up 90 basis points while the S&P 500 was up 2.3%. Additionally, small cap stocks (Russel 2000) were down 7% while the Vektorium Fund Class A was down an estimated 1.51%. Divergence is part of investing and no doubt we do not invest nor is time horizon for your capital one quarter in length, but this divergence is noticeable as the market, for now, is deeply concentrated in the AI hardware ecosystem. There are great businesses in this area and no doubt we are invested in SK Hynix, NVIDIA and several names that do directly benefit from the massive capital expenditure in this once in a lifetime buildout of AI. Additionally, we have and do continue to believe that there is tremendous value in the long-term in smaller and medium-sized companies around the world.
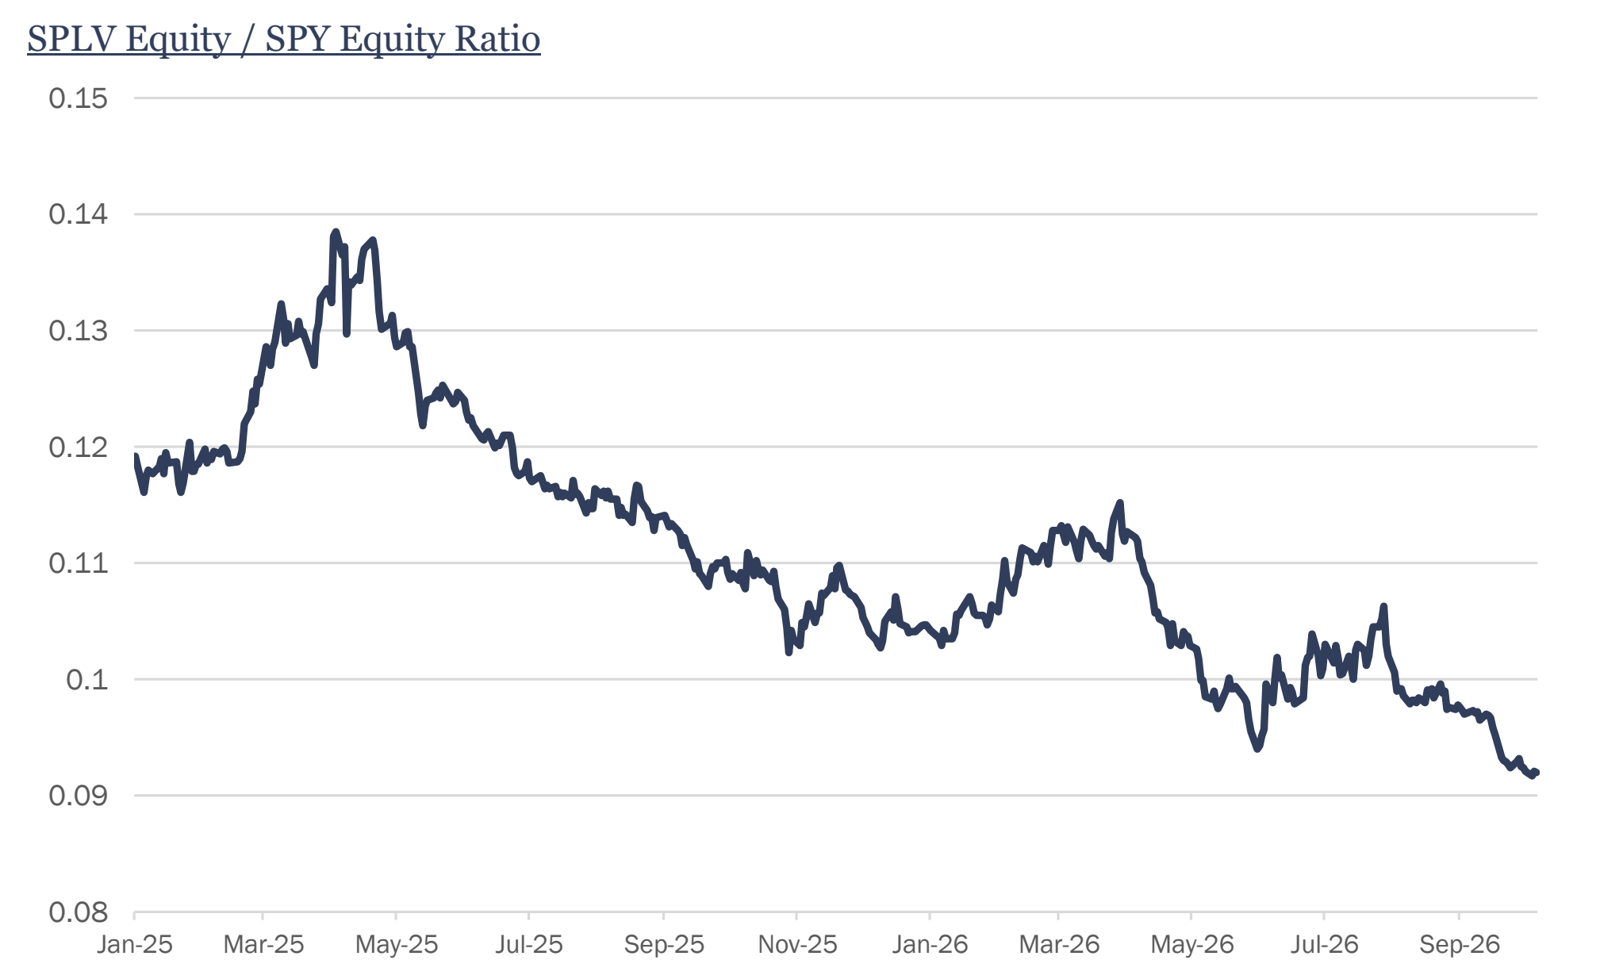
One way to illustrate how narrow the market has been is to look at the S&P low volatility names (SPLV) versus the S&P 500 (SPY US). The chart illustrates how much low volatility stocks (think of these as older economy-type companies) have underperformed the broader market. This illustrates that the large-cap equity rally is really a large cap technology driven rally. We believe that the current ‘shape’ of equities is really AI or not AI, and the ‘not AI’ side of the world has not seen the same ebullient rally.
We are not the only ones who have noticed the relative exceptional performance of the AI space. Insiders have been selling a fair amount of shares in their AI-related businesses as well. Please see a recent Bloomberg article here for a rundown of significant insider selling.
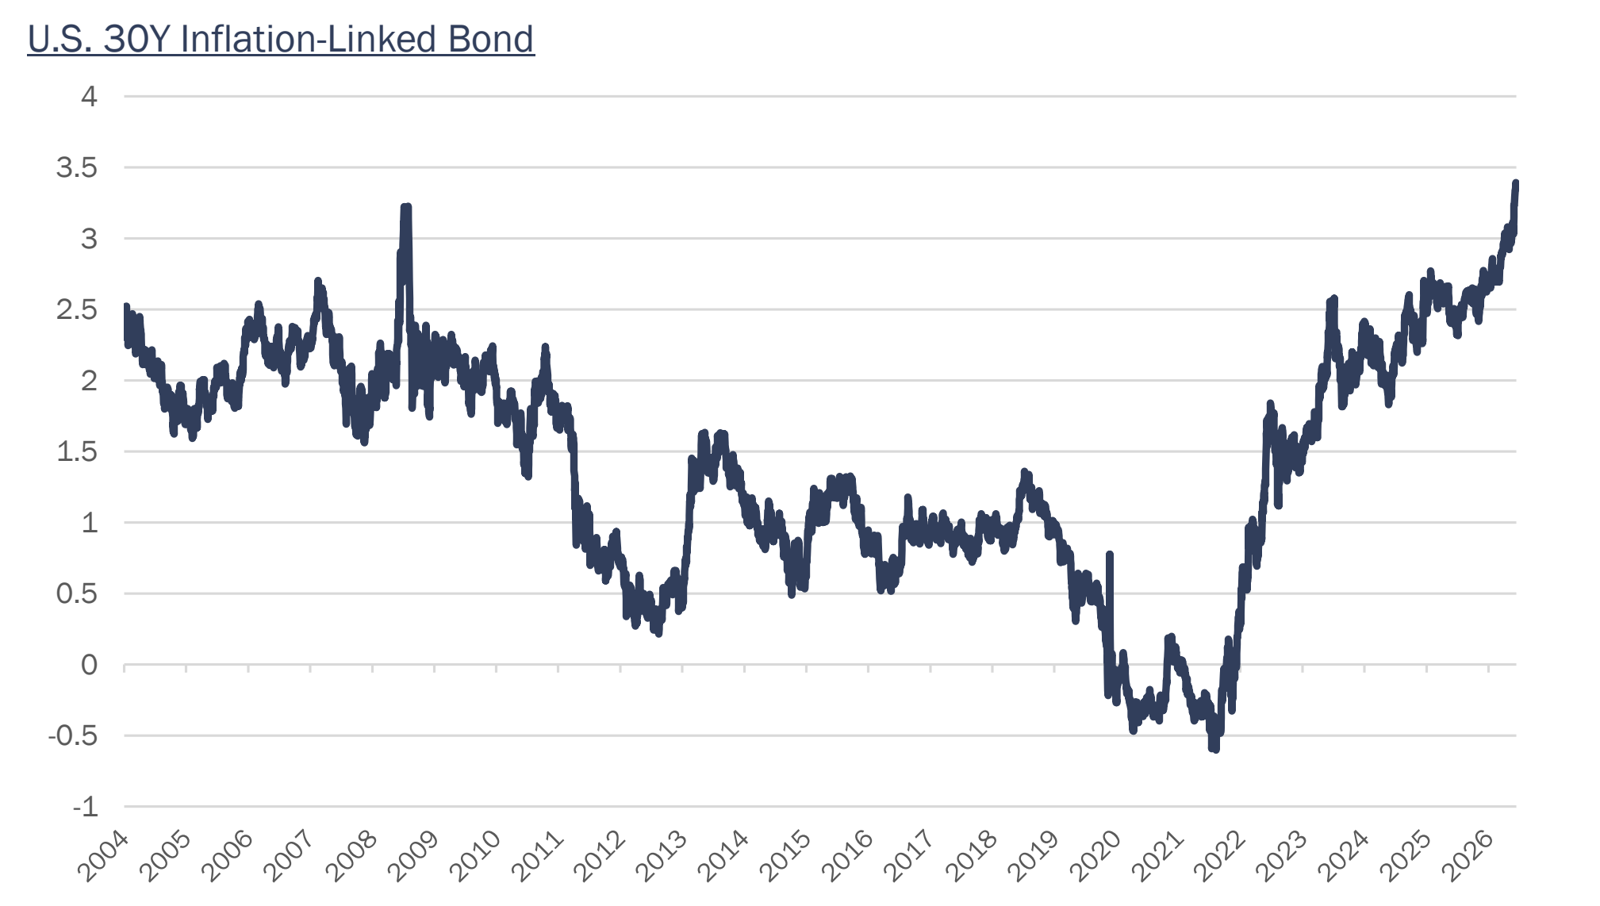
What also worked against us, for now, was a continued rise in interest rates across the globe. We have written about our position in long-dated USD inflation-linked bonds. The real yields on these securities rose more than 30 basis points (0.30%) on the month and contributed to about 35 basis points of drag on performance. As the chart below shows, U.S. 30-year real yields have risen to their highest level since they were issued. With the U.S. economy running at full steam, real GDP is still trending in the 2.5% range, so with real yields on these instruments north of 3.3%, we feel we have a buffer for these bonds. We would look to and have added to the position as yields rise. The current position is about 6% of the fund, and we would be comfortable adding to this position. What would foment a rally would be a slow down in U.S. real growth, a slow down in corporate bond issuance (particularly hyperscalers) or a recognition by the market that REAL yields are historically at very attractive levels for a long-term investor despite the current malaise over nominal yields. We are prepared to wait for this investment to pan out, as we are clipping a healthy coupon on the investment with inflation running north of 3% as well.
Our options portfolio was a slight positive contributor for the month as we did have some hedges on credit that worked in our favour. We had a good-sized position via put spreads on U.S. High Yield debt via the HYG ETF. As bond yields rose across the world, junk bonds felt particular pressure and our put spreads worked well. We have monetized and rolled these positions down and took some profits.
We believe in the near-term markets may continue their narrow focus as the AI capex boom is THE story both financially and economically. However, what has also happened is great businesses that are underfollowed continue to show up as our counterparts in Canada come back from their vast array of corporate meetings with many great ideas. As always, we are thankful to Scott, Bridget and Devon for their tireless research efforts.
We are confident our risk management approach and discipline to balancing opportunity with volatility will serve your capital well in the long-term.
Best,
V
Disclaimer
This Commentary expresses the views of the author as of the date indicated and such views are subject to change without notice. Wealhouse International SEZC has no duty or obligation to update the information contained herein. This Commentary is being made available for educational purposes only and should not be used for any other purpose. The information contained herein does not constitute and should not be construed as an offering of advisory services or an offer to sell or solicitation to buy any securities or related financial instruments in any jurisdiction. Certain information contained herein concerning economic trends and performance is based on or derived from information provided by independent third-party sources. Wealhouse International SEZC believes that the sources from which such information has been obtained are reliable; however, it cannot guarantee the accuracy of such information and has not independently verified the accuracy or completeness of such information or the assumptions on which such information is based. All calculations and data presented is based on unaudited data and is being provided in response to specific request and is intended for internal use only. The information is provided “as is” without warranty of any kind and is subject to adjustments. Such adjustments could have a material impact on the estimated figures and are subject to revision. Wealhouse does not accept any responsibility or liability for the accuracy, content, completeness, legality, or reliability of the information contained herein. No warranties, promises and/or representations of any kind, expressed or implied, are given as to the nature, standard, accuracy or otherwise of the information provided herein nor to the suitability or otherwise of the information to the reader’s particular circumstances.